
Personal Finance Tips for Beginners: 15 Smart Ways to Manage Money and Build Wealth
Personal finance is one of the most important life skills everyone should learn. Whether you are a student, a salaried employee, a business owner, or a young professional, managing your money wisely can help you achieve financial freedom and build a secure future.
Many people work hard to earn money, but they struggle to save, invest, and manage their expenses. The secret to financial success is not always earning a higher income. It is learning how to use your money effectively.
If you are a beginner and want to improve your financial situation, here are 15 practical personal finance tips that can help you save money, reduce debt, invest wisely, and build long-term wealth.
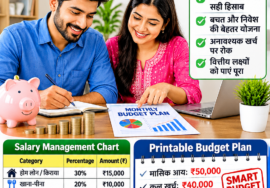
1. Create a Monthly Budget
The first step towards financial success is creating a monthly budget. A budget helps you understand how much money you earn, how much you spend, and how much you can save.
Start by listing your monthly income and expenses, including rent, groceries, electricity bills, transportation, shopping, and entertainment.
Try to follow a simple budgeting strategy that divides your income into different categories. For example:
- 50% for essential expenses.
- 30% for personal wants and lifestyle.
- 20% for savings and investments.
You can adjust these percentages according to your income and financial responsibilities.
2. Start Saving Money Every Month
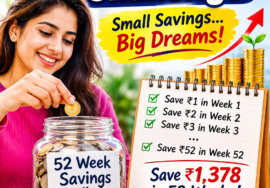
Saving money is the foundation of personal finance. You do not need a huge salary to start saving. Even a small amount saved regularly can make a meaningful difference over time.
Make saving a priority instead of waiting until the end of the month. As soon as you receive your salary or income, transfer a fixed amount into your savings account.
For example, if you earn ₹30,000 per month, try saving ₹3,000 to ₹6,000 regularly.
Remember, consistency is more important than the amount you save initially.
3. Build an Emergency Fund
An emergency fund protects you from unexpected financial situations, such as medical expenses, job loss, urgent home repairs, or other emergencies.
Ideally, beginners should aim to build an emergency fund equal to 3–6 months of essential living expenses.
For example, if your monthly essential expenses are ₹20,000, your emergency fund target should be between ₹60,000 and ₹1,20,000.
Keep this money somewhere safe and easily accessible, such as a suitable savings account or liquid financial instrument. Avoid investing your emergency savings in risky assets like stocks.
4. Start Investing Early
One of the biggest mistakes beginners make is delaying investments. The earlier you start investing, the more time your money gets to grow.
You can explore different investment options, such as:
- Mutual Funds
- Fixed Deposits (FDs)
- Public Provident Fund (PPF)
- Stocks
- Exchange-Traded Funds (ETFs)
- Government savings schemes
Before investing, understand the risk, returns, investment period, and liquidity of each option.
Do not invest simply because someone promises high returns. Always make investment decisions according to your financial goals and risk tolerance.
5. Understand the Power of SIP
A Systematic Investment Plan (SIP) is a convenient way to invest a fixed amount regularly in mutual funds.
For beginners, SIPs can help develop a disciplined investment habit without requiring a large amount of money at once.
For example, suppose you invest ₹5,000 every month through an SIP for 20 years.
- Monthly investment: ₹5,000
- Investment period: 20 years
- Total investment: ₹12 lakh
- Assumed annual return: 12%
- Estimated maturity value: Approximately ₹49.5 lakh
These figures are illustrative, not guaranteed. Mutual fund returns depend on market performance and can be negative.
6. Avoid Unnecessary Debt
Debt can become a major financial burden if you do not manage it properly.
Credit cards, personal loans, and expensive EMIs can reduce your ability to save and invest.
Before taking a loan, ask yourself whether the purchase is necessary and whether you can comfortably afford the repayments.
If you already have multiple debts, focus on paying off high-interest debts first.
Avoid using credit cards for purchases you cannot repay in full by the due date.
7. Learn How to Use Credit Cards Wisely
Credit cards can be useful financial tools when used responsibly. They can help with convenient payments, online shopping, and building a credit history.
However, paying only the minimum amount due can result in high interest charges.
Follow these simple rules:
- Pay your credit card bill in full and on time.
- Avoid unnecessary purchases.
- Keep your credit utilisation under control.
- Check your monthly statements.
- Never spend beyond your repayment capacity.
A credit card should make financial management easier, not create financial stress.
8. Get Health and Term Insurance
Financial planning is not only about saving and investing. Protecting yourself and your family from unexpected financial risks is equally important.
Health insurance can help manage hospitalisation and medical expenses, subject to policy conditions.
Term life insurance can provide financial protection to your dependants if something happens to you during the policy term.
Choose insurance based on your family responsibilities, income, existing coverage, and financial needs.
Remember that insurance is primarily for protection, not a shortcut to wealth creation.
9. Set Clear Financial Goals
Without financial goals, it becomes difficult to manage money effectively.
Set short-term, medium-term, and long-term financial goals.
For example:
Short-term goals:
- Build an emergency fund.
- Buy a smartphone.
- Clear credit card debt.
Medium-term goals:
- Save for a car.
- Plan an international vacation.
- Save for a home down payment.
Long-term goals:
- Build a retirement corpus.
- Purchase a house.
- Create financial security for your family.
Having clear goals makes it easier to choose suitable savings and investment strategies.
10. Understand the Power of Compound Interest
Compound interest is one of the most powerful concepts in personal finance.
It means earning returns not only on your original investment but also on the returns accumulated over time.
For example, if you invest ₹1 lakh at an assumed annual return of 10%, compounded annually, it could grow to approximately ₹2.59 lakh in 10 years.
This is why starting early and remaining invested for the long term can make a significant difference.
11. Track Your Daily Expenses
Small expenses can quietly damage your monthly budget.
Ordering food online, unnecessary shopping, unused subscriptions, and frequent entertainment expenses may seem insignificant individually, but they can add up.
Maintain a record of your daily expenses using a notebook, spreadsheet, or budgeting application.
Review your spending every month and identify areas where you can save more money.
12. Increase Your Income Sources
Saving money is important, but increasing your income can accelerate your financial progress.
You can explore additional income opportunities based on your skills and interests.
Some popular options include:
- Freelancing.
- Blogging.
- YouTube content creation.
- Online teaching.
- Affiliate marketing.
- Digital product creation.
- Part-time business activities.
However, avoid schemes that promise guaranteed high income without effort. Focus on developing valuable skills and building sustainable income sources.
13. Improve Your Financial Knowledge
Financial education helps you make better decisions about money.
Learn the basics of budgeting, taxation, insurance, mutual funds, stock markets, retirement planning, and banking.
You can improve your knowledge through financial books, educational videos, trusted websites, and investment courses.
Some popular books for beginners include:
- Rich Dad Poor Dad by Robert Kiyosaki.
- The Psychology of Money by Morgan Housel.
- The Intelligent Investor by Benjamin Graham.
- The Richest Man in Babylon by George S. Clason.
Reading about personal finance regularly can help you develop better financial habits.
14. Plan for Retirement Early
Retirement planning should not be postponed until you reach your 40s or 50s.
Even if retirement seems far away, starting early gives your investments more time to grow.
Explore suitable options such as EPF, PPF, NPS, mutual funds, and other retirement-oriented investments.
Calculate how much money you may need after retirement, considering inflation, lifestyle expenses, and healthcare costs.
A disciplined investment strategy can help you work towards financial independence.
15. Review Your Financial Progress Regularly
Personal finance is not a one-time activity. Your income, expenses, responsibilities, and financial goals may change over time.
Review your financial situation every three or six months.
Check your savings, investments, debts, insurance coverage, and progress towards your goals.
If necessary, adjust your budget and investment strategy to match your changing financial needs.
Conclusion: Start Your Personal Finance Journey Today
Managing money wisely is the first step towards building a financially secure future. You do not need to be rich to start your personal finance journey. You simply need discipline, patience, and the willingness to make better financial decisions.
Start with small steps: create a budget, save regularly, build an emergency fund, avoid unnecessary debt, and invest according to your financial goals.
Remember, financial freedom does not happen overnight. It is the result of consistent financial habits and smart decisions made over many years.
Start today, save consistently, invest wisely, and let time work in your favour.
Disclaimer: This article is for educational purposes only and should not be considered financial or investment advice. Investment decisions should be made after considering your financial situation and risk tolerance.